
Private vs. Institutional Real Estate Lenders: A Georgia Investor’s Guide
Choosing a real estate lender involves more than comparing interest rates. Georgia investors should also review total borrowing costs, property eligibility, underwriting requirements, closing conditions, and repayment terms. The right fit depends on your property, project, and financing needs.
What is the difference between private and institutional lenders?
Private real estate lenders provide financing outside traditional bank lending channels. Institutional lenders can include banks, credit unions, and larger lending organizations, although their products and processes vary.
These categories are broad. A private lender may have strict underwriting requirements, while an institutional lender may offer specialized investment-property financing. Compare the specific loan and process rather than relying on the lender’s label.
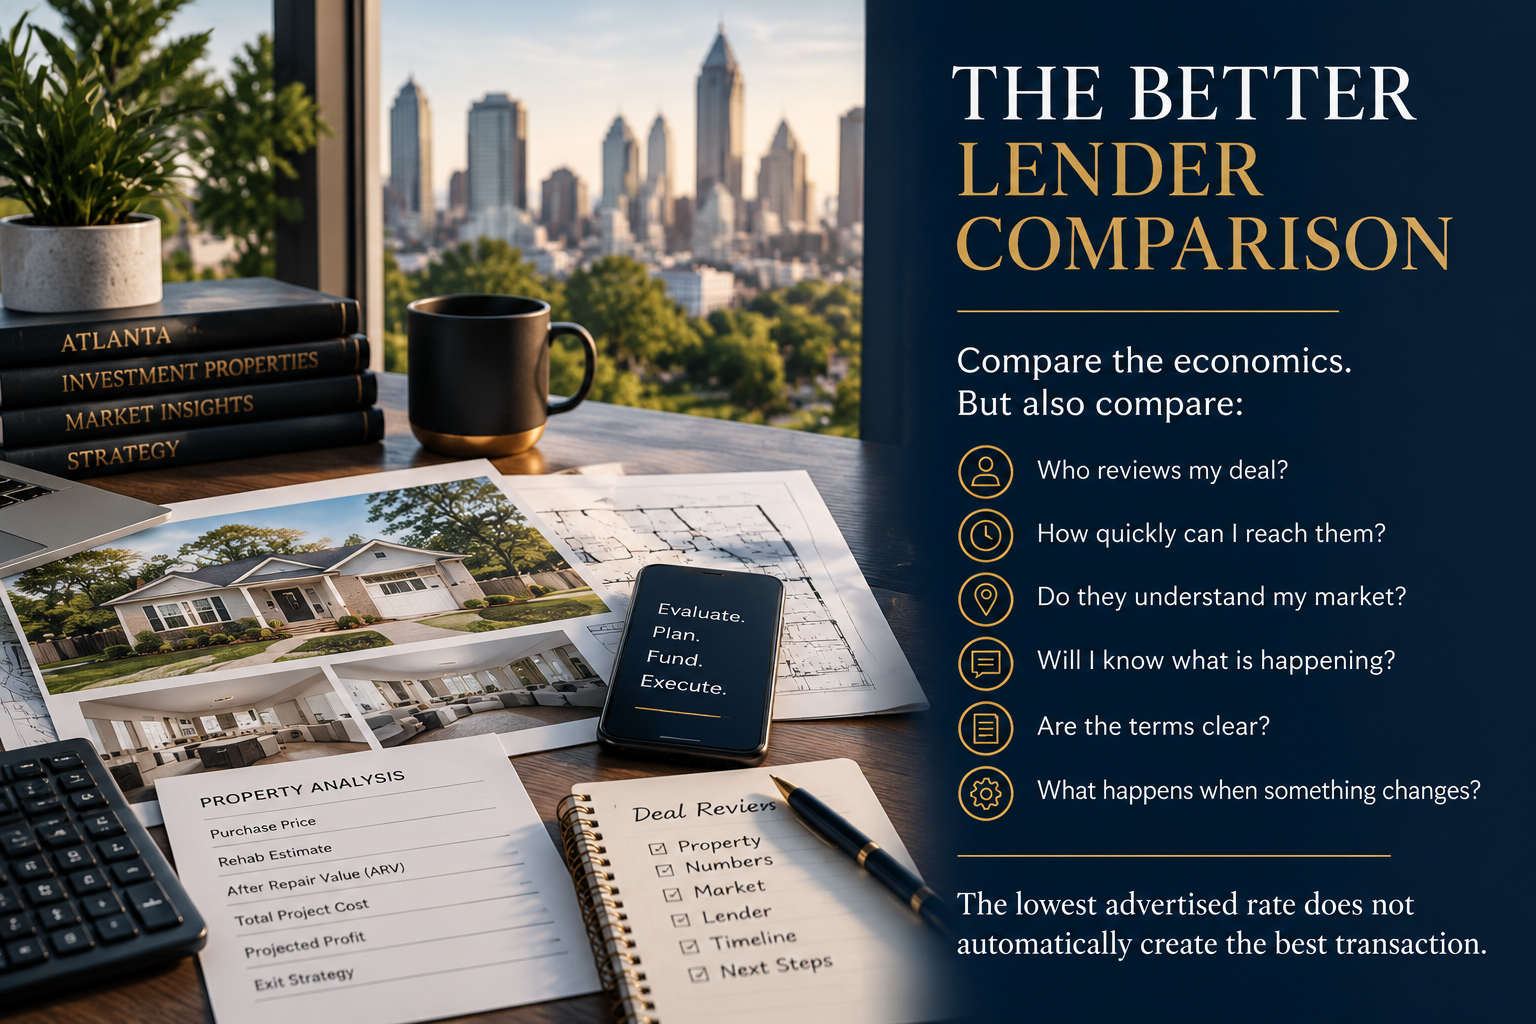
Use the following checklist to compare lenders and written loan proposals on the same basis.
How should you compare total borrowing costs?
Compare the expected dollar cost over the period you plan to hold the loan. Review interest, origination points, lender fees, third-party charges, and any applicable minimum-interest or prepayment provisions.
Ask whether interest is calculated on the full commitment or only on funds advanced, particularly when renovation financing involves draws. Also review what additional costs could apply if the project takes longer than expected.
A lower advertised rate does not necessarily produce a lower total cost. The comparison depends on the loan amount, fee structure, funding schedule, and actual repayment date.
Which lender fits your property and project?
Confirm that each lender considers your property’s location, type, condition, and intended use. Then compare the requested borrower contribution, experience, documentation, and exit strategy.
For a renovation project, ask how the rehab budget is reviewed and how funds are released. Draw procedures and inspection requirements can affect the cash you need during construction.
Brey Lending focuses on Georgia investment-property financing. An initial conversation should establish whether the property and proposed transaction fit its lending criteria.
What should you verify about closing speed?
Ask what must happen before the lender can fund—not simply how quickly the lender can respond. Initial feedback, approval, and funding are different stages.
Request a clear explanation of outstanding conditions, including valuation, title, insurance, borrower documents, and required funds. Ask who coordinates each stage and how changes to the closing date are handled.
Evaluate any proposed timeline against the details of your transaction. Neither a private nor an institutional lender should be assumed to meet a deadline solely because of its category.
When might an institutional lender be a better fit?
An institutional lender may be worth considering when its financing product fits the property, you can meet its documentation requirements, and its process aligns with your schedule.
Depending on the product, it may offer a repayment structure or total cost that suits your investment plan. Compare the complete written terms rather than assuming that an institutional offer is always less expensive.
If an existing lender already meets your needs, maintaining that relationship can be sensible.
When might a local private lender be worth considering?
A local private lender may be worth considering when its loan structure fits a short-term investment need and direct communication is important to the transaction.
Ask who evaluates the property, who communicates underwriting conditions, and who can discuss changes during the project. Local familiarity is most useful when it supports a realistic assessment of the collateral, renovation plan, and repayment strategy.
Compare these service considerations alongside cost, borrower contribution, and repayment terms. Direct access does not remove underwriting requirements or guarantee funding.
Have a Georgia investment property to discuss?
Start with the property address, intended exit strategy, target closing date, and current photos or video. Brey Lending can review the initial information and identify what needs to be verified next.
Call/Text: 470-470-9894
Schedule a Call